Automakers await IRS guidance on Inflation Reduction Act to boost Biden's 'electric vehicle revolution'
With the Inflation Reduction Act expanding tax credits and providing funding, the U.S. electric vehicle industry is poised to accelerate, but automakers and industry groups are awaiting detailed implementation rules from the Internal Revenue Service (IRS) to clarify complex requirements such as domestic sourcing of battery components and critical minerals, avoiding consumer confusion and impacts on investment.
Industry stakeholders say the labor, equity, and domestic content rules in the 2022 Inflation Reduction Act (IRA) should not make the EV purchasing process overly complex or force automakers to make burdensome procurement adjustments.
A report released by Energy Innovation in January 2023 found that with the expanded tax credits and funding support from the IRA, electric vehicles are expected to "shift into high gear," accelerating the formation of U.S. supply chains and charging infrastructure networks.
Research by Atlas Public Policy in September 2022 showed that the total federal funding for electric vehicles provided by the IRA, together with the Infrastructure Investment and Jobs Act, is "nearly 30 times" the sum of all previous federal programs.
However, Nick Nigro, founder of Atlas Public Policy, pointed out that the complexity of the current rules regarding tax credit eligibility could "undermine consumer confidence and investment in the EV industry." He added, "When eligibility requirements cover battery components and critical battery material procurement, the situation becomes even more complex."
Based on more than 880 stakeholder comments received by the IRS (including comments from Ford, Dow, and Samsung), the industry widely calls for clear guidance. These comments request that the IRS provide direction on how to implement the IRA provisions.
Katherine Stainken, Vice President of Policy at the Electrification Coalition, said that if IRS guidance can "balance the needs of drivers, the EV industry, and the intent of the law," it will create a "new future" for U.S. transportation. "Guidance may be complex, but months of delay are insignificant compared to decades of transformation," she said.
Policy analysts believe the Treasury Department must fulfill the law's intent to revitalize the U.S. auto industry. This will require automakers to identify and verify the complexity of battery component and critical mineral sourcing in a way that is easy for consumers to understand—a thorny challenge that stakeholders agree on.
Positive Signals
Data from the Environmental and Energy Study Institute (EESI) shows that the IRA's core initiative to support EVs is providing $12.5 billion to extend and expand the federal tax credit of up to $7,500 for EV buyers. But stakeholders agree that its domestic sourcing and labor requirements will be far more complex than the current domestic final assembly obligation.
The IRS stipulates that the new vehicle tax credit only applies to buyers with annual income not exceeding $300,000 (joint filing), $225,000 (head of household filing), or $150,000 (single filing), and the new vehicle price does not exceed $55,000, while new trucks, vans, or SUVs must not exceed $80,000.
The used vehicle tax credit covers 30% of the cost of an eligible vehicle (at least 2 years old, priced at no more than $25,000), with a maximum credit of $4,000, also subject to tiered income limits.
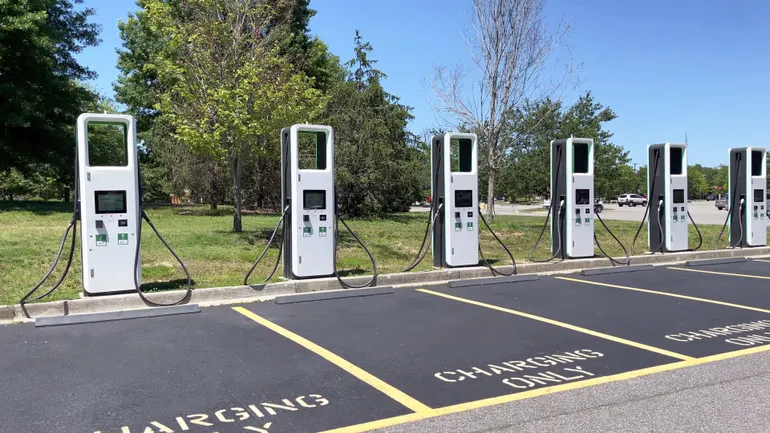
The IRA retains the $1,000 residential charger tax credit and increases the commercial charger tax credit (30% of cost) from a maximum of $30,000 per location to $100,000, while adding a restriction: the new credit only applies to chargers in non-urban areas or low-income population areas.
The White House IRA guide states that IRA grants and loans will also fund state and local transportation electrification efforts, as well as domestic battery and critical mineral manufacturing and recycling. The guide also notes that access to these grants and loans is expanded to include a "direct pay" option, allowing entities with limited tax liability or tax-exempt entities to receive upfront cash rather than tax deductions.
The Energy Innovation report states that IRA tax credits can reduce the cost of light-duty EVs by up to $9,050 per vehicle, with sales potentially increasing by 67% by 2032, depending on Treasury guidance. The report also notes that these credits will enable "stricter federal vehicle standards to be implemented at lower cost and deliver greater benefits to consumers."

IRA and Treasury's Initial Plans
The White House IRA guide states that the IRA requires battery components and critical minerals to be sourced from the United States or free trade agreement partner countries, and not from "foreign entities of concern."
But Genevieve Cullen, President of the Electric Drive Transportation Association (EDTA), and others say that only guidance expected to be released by the Treasury Department at the end of March will clarify how these sourcing requirements will be measured and applied to tax credits.
Stainken of the Electrification Coalition believes that the Treasury Department's December 2022 white paper offers initial interpretations of the IRA's critical mineral and battery component requirements, and these interpretations "seem logical," with most stakeholders largely in agreement.
Cullen of EDTA noted that the Treasury's proposal allows for up to $3,750 for meeting battery component requirements and up to $3,750 for meeting critical mineral requirements under the new vehicle tax credit.
The Treasury proposes that 50% of the total value of battery components be domestically sourced in 2023, increasing to 60% in 2024 and 2025, then increasing by 10% each year until reaching 100% after 2028.
For critical minerals, the Treasury recommends that vehicles placed in service in 2023 have 40% of critical minerals extracted or processed in the United States or free trade agreement countries, or recycled in North America; this increases by 10% each year, reaching 70% in 2026, and rising to 80% after 2026.
The Treasury white paper states that identifying "the extraction, processing, and recycling of critical minerals" and "where these activities occur" in multi-step supply chains is essential for compliance certification. The white paper also proposes a three-step "transition rule" through 2024 to address complexity, giving manufacturers "time to develop the necessary capabilities."
The Treasury proposes that, first, battery manufacturers should identify the critical mineral supply chain; second, determine whether the extraction, processing, or recycling of critical minerals meets domestic requirements; and finally, manufacturers calculate the proportion of these critical minerals to the total value of each battery.
But stakeholders say the Treasury has not resolved other complex issues. The Treasury acknowledges that "constituent materials" may "contain critical minerals used to produce 'battery components,'" creating uncertainty in the proposed assessment of total battery component value.
Stainken of the Electrification Coalition said implementation of the new rules could be complex, "but it is crucial to achieving the law's intent to transform transportation." She cautioned that the Treasury "seems to be methodically clarifying issues," but "regardless of the next proposed guidance, final rules will be issued in about six months, which could further affect compliance."
Meanwhile, the Treasury is reviewing more than 880 stakeholder comments, many of which hold conflicting views on key issues.

Three Key Questions
The U.S. EV ecosystem is awaiting answers to the following questions: how to make IRA tax credit eligibility simple and understandable for car buyers; what the maximum tax credit is for EV charging infrastructure; and how to reconcile the IRA with the complexity of global supply chains.
Can Car Buyers Understand?
Plug-In America reports that vehicle tax credit eligibility can currently be confirmed by entering the Vehicle Identification Number (VIN) into the "DOE Decoder." But Plug-In America acknowledges that significant questions remain about how domestic content, buyer income, and automaker pricing will be verified under IRA rules.
Nigro of Atlas said: "The simpler it is for consumers, the better," because a lack of clarity "could create market confusion," and "processes that consumers find difficult to understand could discourage them from buying EVs."
Recent surveys confirm this concern. GfK AutoMobility's November 2022 study showed that among car buyers interested in EVs, 93% said tax credits were "somewhat important" or "very important" to their purchase decision. Of those who said tax credits were "very important," 70% said they would change plans if their preferred model did not qualify, and 15% said they would not buy an EV.
Nigro warned that an overly complex process "could determine whether car buyers receive thousands of dollars in tax credits and whether the EV industry receives billions of dollars in investment."

What Is a Charging Station?
McKinsey & Company's April 2022 analysis shows that to achieve the federal goal of zero-emission vehicles accounting for 50% of annual new vehicle sales by 2030, the United States may need to increase charger installations by nearly 20 times.
Utilities such as Con Edison and Arizona Public Service say they will not finalize charging deployment plans until the Treasury Department issues guidance.
Kellen Schefter, Senior Director of Electric Transportation at the Edison Electric Institute (EEI), said the Treasury may confirm that investor-owned utilities can "apply credits to electrical equipment or power service upgrades" and "install and own" EV chargers and related infrastructure.
Under the law, this construction is supported by the IRA's allowed tax credit for each "single item" of charging property installed. James Ellis, Director of Energy and Utilities at EV Connect, said the increase in the tax credit to $100,000 "will support the more expensive fast chargers needed at high-demand sites, such as commercial fleet parking lots in low-income areas," as well as charging along "rural corridors connecting communities."
But Ellis noted that charger credit eligibility depends on wage and apprenticeship requirements that have not yet been finalized, as well as low-income areas that are not yet fully defined. He emphasized that the meaning of "single item" must be clarified.
Ellis said "single item" could mean one charging station or one charging port; a dual-port station serving two vehicles could correspond to a $100,000 or $200,000 cap, and a $30,000 or $60,000 tax credit. He added that this is crucial "as demand for greater charging capacity grows" and more sites adopt the "convenience store-gas station" model with multiple chargers and ports.
Ellis and other stakeholders said "single item" could also refer to utility system upgrades, equipment to meet new charger loads, or site improvements. The EDTA and Natural Resources Defense Council (NRDC) submissions also raised the "single item" issue, with EDTA stating these issues are important for avoiding deployment of outdated technology and supporting installation of solar and bidirectional chargers.
Ellis added that private charger builders, utilities, and tax-exempt entities such as rural electric cooperatives, publicly owned utilities, and nonprofits all need this guidance; these entities can now use the "direct pay option" to build and own charging infrastructure.
What Does "Domestic" Mean?
Christopher A. Smith, Ford's Chief Government Affairs Officer, wrote in comments to the IRS that the United States is "at an inflection point." Guidance can maintain America's "position as an economic and technological leader on the world stage" and ensure "the EV revolution is built for America."
Most stakeholders agree. Nigro of Atlas said the IRA helps "drive an overall U.S. policy shift toward building an EV industry, avoiding the mistakes of the fossil fuel auto industry or abuses in human rights and the environment by some battery supply chain suppliers."
But RMI acknowledged in comments to the Treasury that this may be difficult to achieve before automakers "realign their supply chains and record-keeping" to meet the new domestic content requirements. Resources for the Future's submission added that two key challenges are that "only a small portion of critical minerals" come from the United States or free trade agreement countries, and "most battery manufacturing" occurs outside North America.
NRDC wrote: "The global supply chain of vehicles, components, batteries, and their minerals is an extremely complex network that no one can accurately map at present."
RMI said that inclusive definitions of extraction, processing, manufacturing, recycling, and value, along with better supply chain tracking, can "increase supply chain transparency" and improve "chain-of-custody reporting with end-to-end traceability, as well as cooperation across the full value chain from suppliers and recyclers," enabling implementation under IRA complexity.
RMI added that the International Material Data System (IMDS) and the Global Battery Alliance Battery Passport databases both offer digital platforms that can track sourcing and "provide clear information for dealers and consumers."
But submissions from BYD's U.S. subsidiary (the American subsidiary of China's BYD) and the Coalition for American Battery Independence both said guidance is still needed, especially regarding the meaning of "foreign entity of concern." BYD wrote that a U.S. subsidiary "established and operated under U.S. law" should not be excluded from tax credit eligibility absent evidence of "government control by a foreign entity of concern."
Nigro of Atlas said the IRA "aims to build a sustainable domestic supply chain for the EV transition," but Treasury guidance is needed. He added: "When guidance comes out, companies that are ready to comply will be first movers and gain a huge competitive advantage."